
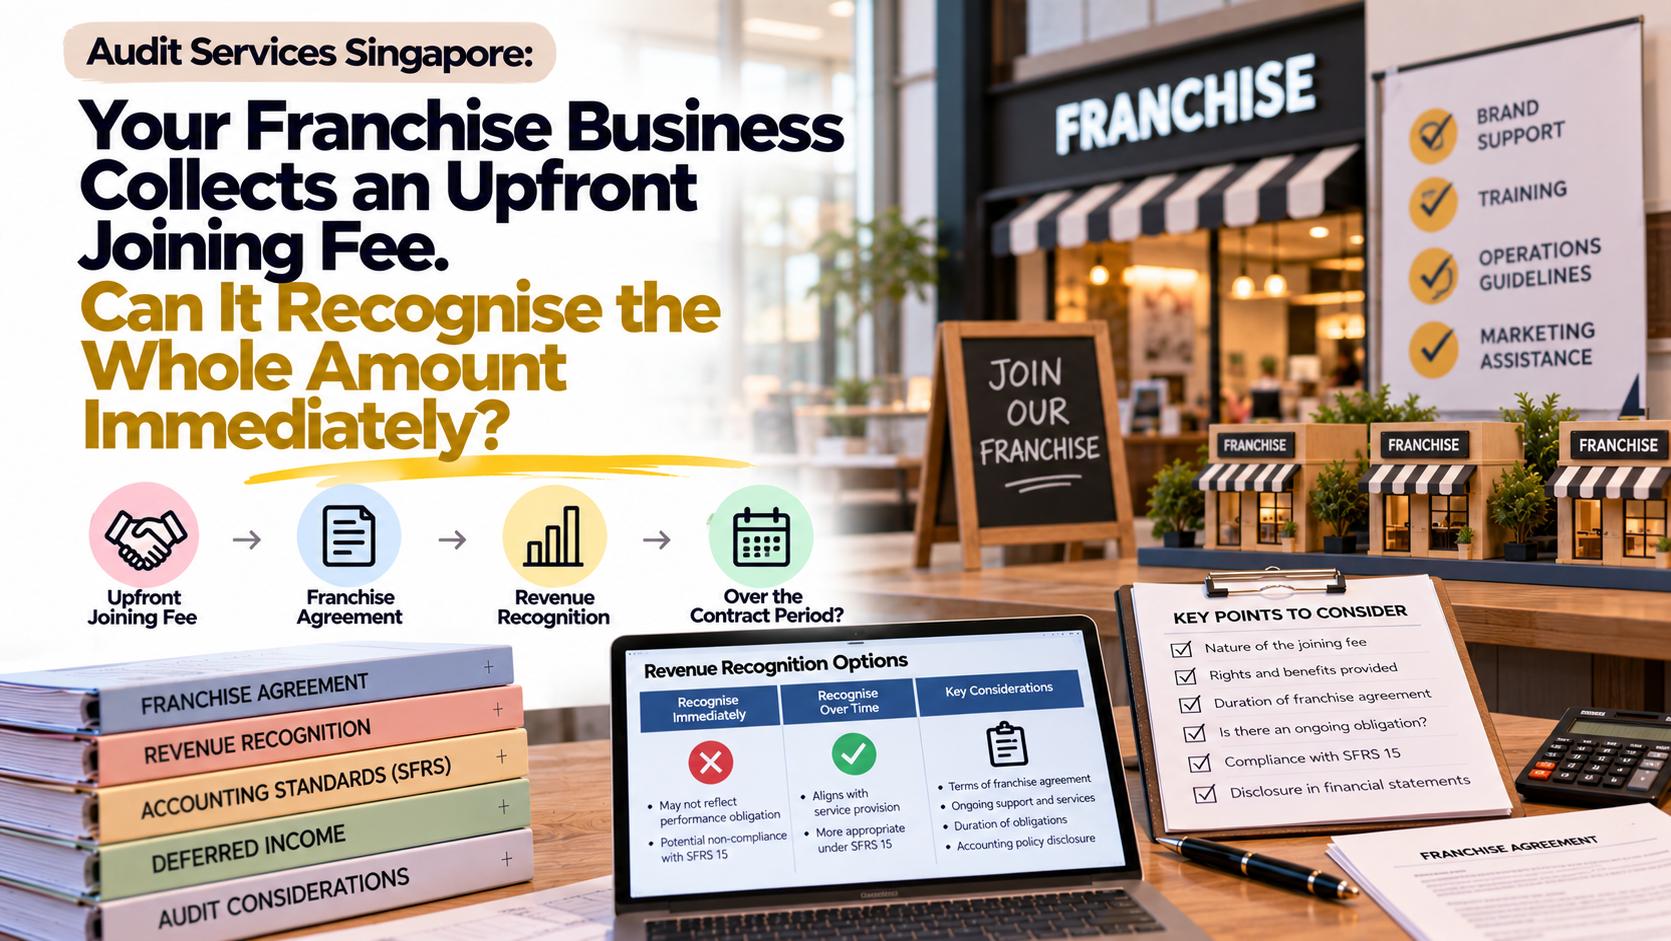
For a growing franchise business, a new agreement represents more than another outlet. It brings a new operator into the network, extends the brand’s reach and creates an opportunity to serve more customers. An upfront joining fee can also provide welcome cash to support the next stage of expansion.
However, the financial statements need to explain more than the money received. Behind each joining fee may be a combination of training, franchise rights, equipment and support that the business must provide over time. Reporting the entire payment as revenue at signing can give an incomplete picture of what has been earned and what remains to be delivered.
Credon PAC provides audit and assurance services in Singapore, alongside accounting and financial reporting support. For franchise owners, the joining-fee question illustrates why understanding the commercial agreement is essential to understanding the accounts. Clear reporting starts with the promises behind the payment.
When those promises are reflected consistently in the financial records, management gains a more useful view of expansion: the cash collected, the revenue earned and the commitments carried into future periods.
When Franchise Growth Creates a Reporting Challenge
In the early stages of a franchise network, the founder may know every agreement personally. The first few outlets may operate under similar terms, with the same training programme and support arrangements. Finance can clarify questions directly with the people who negotiated the contracts.
As the network grows, those arrangements may become more varied. One franchisee receives equipment as part of the package, another negotiates additional launch support, and a third secures different renewal terms. A single invoice description such as “joining fee” may conceal these differences.
If the accounting process continues treating every receipt in the same way, the records can fall behind the commercial reality. The issue may become visible only when management reviews annual results or the auditor asks what supports the revenue recognised.
For businesses evaluating audit services Singapore providers offer, this is a useful point to consider: the audit needs to reflect how the business actually earns its income. A larger network requires a reporting process that can accommodate contractual differences without losing consistency.
Credon’s Starting Point: Understanding the Business Behind the Figures
Credon describes understanding the client’s business structure and reporting requirements as the starting point of its audit process. Applied to a franchise business, that context includes how agreements are negotiated, what franchisees receive and how delivery is documented.
The questions are practical. What does the joining fee purchase? Which activities occur before opening? Which obligations continue after the outlet begins trading? Are the terms consistent across the network?
Management can make those discussions more productive by bringing together the standard agreement, significant variations and the records used to track delivery. That allows the accounting assessment to address the actual arrangement rather than rely on a payment label.
The result sought is a clear connection between the commercial promise and the reported figure. Management remains responsible for its accounting judgments, while the auditor independently evaluates the financial statements and supporting evidence.
Why Receiving the Fee Does Not Settle the Revenue Question
A joining fee may be payable immediately and described as non-refundable. Those terms matter commercially, but they do not necessarily establish that the franchisor has already earned the full amount.
Under SFRS(I) 15 or FRS 115, as applicable, revenue reflects the transfer of promised goods or services. The upfront-fee guidance distinguishes genuine deliverables from initial activities that merely prepare the business to fulfil the contract.
If the initial activity does not transfer a promised service, the payment may represent an advance for future delivery. Where a distinct service is provided at the outset, an appropriately allocated amount may be recognised when that obligation is satisfied.
The practical implication is that neither immediate recognition nor automatic deferral of the whole fee should be the default. The conclusion needs to follow the agreement and the applicable reporting framework.
Making the Franchise Package Clearer
A useful review begins by mapping the package from the franchisee’s perspective. The agreement may include access to the brand, initial training, equipment, systems and continuing support. Some of these promises may be distinct, while others may need to be considered together.
Internal administration also needs to be identified separately. Preparing records or processing an application may be necessary work without creating a separate service transferred to the franchisee. The fact that an activity costs the franchisor money does not determine the revenue it earns.
The franchise licence requires particular attention. Its nature affects whether the related promise is fulfilled over time or at a point in time. Ongoing activities affecting the intellectual property and the relationship between the licence and other services need to be assessed.
For management, a written map of the promises can also expose operational gaps. If continuing support is included in the agreement, someone needs to be responsible for delivering and documenting it after the launch team moves to the next outlet.
Turning the Agreement Into a Supported Revenue Schedule
Once the performance obligations have been identified, the contract price needs an appropriate allocation. Where there are multiple obligations, relative stand-alone selling prices generally provide the basis, subject to the standard’s specific requirements.
The commercial invoice may not supply that allocation. A training programme described as complimentary may still have value, while a large amount labelled “initial fee” may relate partly to future services.
Management should retain the evidence and assumptions supporting the allocation. It should also explain the recognition period or delivery milestone for each component. The schedule then becomes a record that can be maintained as the agreement progresses.
This is where a structured reporting process becomes valuable. Instead of deciding the treatment again whenever cash arrives, finance works from an approved assessment, updates it for changes and reconciles it to the ledger.
A Practical Illustration of Cash and Revenue
Consider a hypothetical franchise agreement with a fixed transaction price of S$120,000, paid at commencement. This is an illustrative example, not a Credon client case.
Assume the assessment identifies two distinct obligations: initial training and franchise access provided evenly over five years. Supported stand-alone selling prices are S$20,000 for training and S$130,000 for access. There are no other fees, renewal rights, variable royalties or significant financing effects in this simplified example.
Allocating S$120,000 in proportion to those values assigns S$16,000 to training and S$104,000 to access. Assume the training is completed at commencement and its allocation is recognised then.
If even recognition over 60 months appropriately reflects the access obligation, S$20,800 is recognised for the first 12 months of access. Total first-year revenue is therefore S$36,800, with S$83,200 remaining as a contract liability.
The business has received S$120,000 in cash, but it has not earned S$120,000 of revenue under these assumptions. That distinction helps explain why a strong collection month and a strong revenue month are not always the same thing.
What That Difference Means for Expansion Decisions
The example matters beyond the annual accounts. If management treats every joining-fee receipt as current earnings, it may overestimate the resources generated by completed activity.
A portion of the cash may need to support obligations delivered later. Training teams, systems and network support can continue consuming resources after the initial payment has been collected. Expansion planning should take those future commitments into account.
This does not mean a contract liability is a separate pot of cash that must always remain untouched. It means that management should understand the work still owed and plan how the business will fund it.
Reporting cash receipts, recognised revenue and remaining obligations separately gives owners a clearer basis for evaluating growth. It helps distinguish the success of signing new franchisees from the economics of supporting the existing network.
Building Evidence as the Network Develops
A well-supported revenue schedule depends on operational records. Training completion, equipment delivery and the availability of contractual rights may each require different evidence.
Give each agreement a clear reference and connect it to the relevant documents. Record important dates, approved changes and the people responsible for confirming delivery. Finance should be able to trace a recognised amount back to both the contractual promise and the supporting event or service period.
Review exceptions promptly. An outlet that opens late, changes location or receives additional services may no longer follow the original schedule. Renewal and termination terms may also require further assessment.
Keeping this information current reduces reliance on memory at year-end. It also gives the audit team a more coherent explanation than a collection of signed contracts and bank statements without the reasoning connecting them.
Bringing Financial Reporting and Audit Preparation Together
Credon’s accounting services include bookkeeping, financial reporting and support for management accounts. These capabilities are relevant to the broader challenge of maintaining organised information as a business grows.
For a franchisor, useful reporting can bring together contract balances, recognised revenue and outstanding collections. Supporting records should distinguish initial fees from royalties, equipment sales and other payment streams.
The accounting work and independent audit have different purposes. The appropriate scope of any services must reflect the engagement and applicable independence requirements. For management, the practical priority is to ensure that responsibilities are clear and that the records support the financial statements.
An organised reporting process gives the audit a stronger starting point. It also means that owners can review the business during the year using information that reflects more than the latest cash receipts.
Keeping the Accounting Aligned With Commercial Changes
A growing franchise network rarely stands still. Management may revise the joining package, introduce new support services or offer different terms to enter another market. Those changes should reach finance before the old accounting approach is applied automatically.
Establish a review point when new contract templates or material exceptions are approved. The commercial team should explain what changed, while finance assesses whether the allocation or recognition pattern needs updating.
Renewal rights also deserve attention. Depending on the arrangement, they may affect the assessment beyond the initial contractual period. The recognition schedule should be supported by the relevant rights and obligations, rather than an assumption that every contract ends economically on its stated expiry date.
This discipline helps the business scale a consistent process while still recognising genuine differences. Consistency comes from applying the same principles to the facts, rather than forcing every agreement into the same entries.
A Clearer Financial Story With Credon
Franchise expansion is an achievement worth reporting accurately. New agreements, cash collections and outlet openings each tell part of the story. The financial statements should also explain when value is delivered and what commitments remain.
Credon’s audit and financial reporting services provide a relevant point of contact for businesses reviewing these questions. For a franchisor preparing for audit, a practical first step is to assemble the agreements, management’s revenue assessment and the supporting contract schedules.
That preparation creates a more focused discussion about the business model and the figures. It helps management explain why a fee has been recognised immediately, over time or across several obligations.
For owners considering audit services Singapore firms provide, the joining fee is an opportunity to examine whether financial reporting has kept pace with growth. Contact Credon PAC to discuss your audit requirements and the information needed to support a clear, evidence-based review of your franchise revenue.