
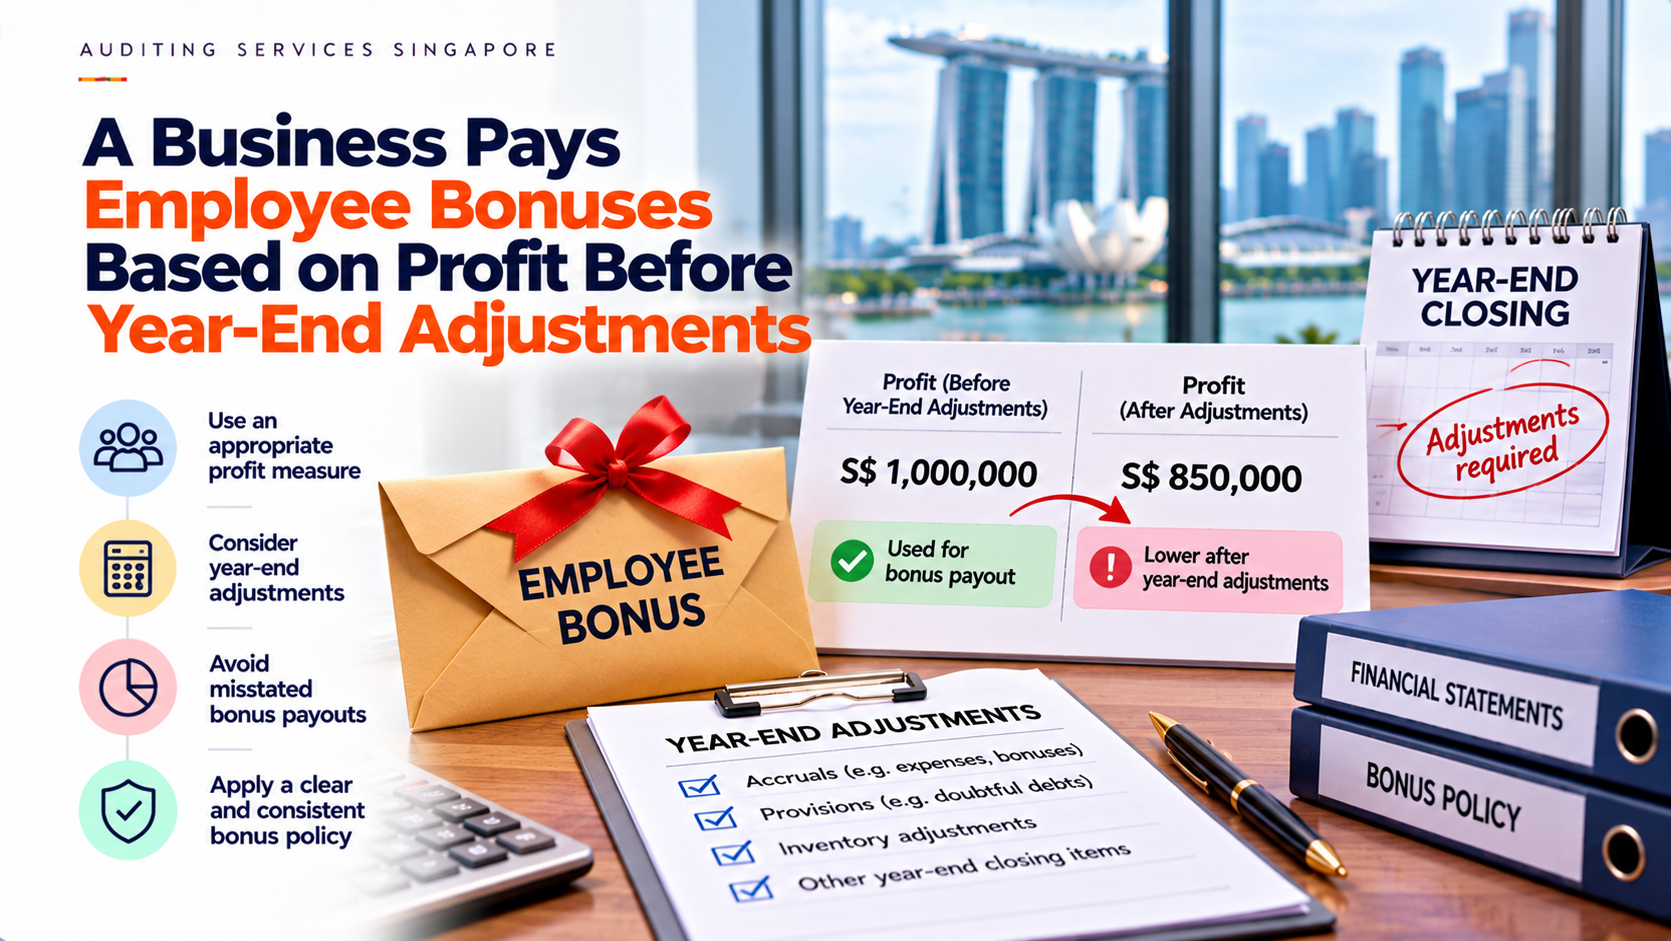
The year-end management accounts show a strong profit. Sales have exceeded expectations, employees have worked hard and management wants to recognise their contribution promptly. A bonus pool is calculated, approved and paid before the finance team completes its final review.
Several weeks later, the position changes. Supplier invoices arrive for work completed before year-end, customer rebates are confirmed and an inventory review identifies stock that needs to be written down. The business remains profitable, but the figure used to calculate the bonuses was higher than the completed accounts support.
The issue is not whether employees deserved recognition. It is whether the company used a sufficiently reliable financial measure when making its commitment. Credon PAC’s accounting and financial reporting services are relevant to improving the information behind these decisions. For management, the starting point is to distinguish provisional results from a completed basis for calculating rewards.
Define What “Profit” Means in the Bonus Arrangement
A promise to pay a percentage of profit can appear straightforward until finance tries to calculate it. The arrangement may leave unclear whether profit is measured before tax, after tax, before bonuses or after the bonus expense itself. It may also be unclear whether the measure relates to the entire company, a department or a particular project.
These differences can produce materially different outcomes. A department’s contribution before shared costs is not the same as the company’s final profit. Likewise, a management performance measure may exclude items that remain part of the statutory accounts.
Review the written scheme and previous communications before performing the calculation. Establish the reporting period, relevant entity, calculation basis and treatment of adjustments. Where the wording is ambiguous, resolve it through the appropriate management and employment advice rather than allowing payroll to choose an interpretation.
Understand How Complete the Management Accounts Are
Management accounts can be useful even when some estimates remain provisional. The difficulty arises when a preliminary figure is presented as though all significant year-end matters have been resolved. Decision-makers need to know what is still outstanding.
Finance should identify the major reconciliations and reviews completed before the bonus proposal is submitted. These might include supplier liabilities, customer balances, inventory, payroll accruals and fixed assets. Explain any material information still awaited and whether it could change the result.
A short completion summary can make this visible. It should state which figures are reasonably supported, which depend on estimates and which remain under investigation. Management can then assess the uncertainty instead of discovering it only after employees have received payment.
Bring Missing Costs Into the Review
An invoice received in January may relate to services delivered in December. If the cost was omitted from the year-end accounts, the preliminary profit may be overstated. Similar gaps can arise with freight, subcontractors, utilities and professional fees.
Ask operating departments to identify work received but not yet invoiced. Compare purchase orders, delivery records and supplier correspondence with the ledger. An open purchase order does not automatically represent an expense, but it can help identify items requiring investigation.
The review should also cover employee-related costs. Overtime, commissions and other earned benefits may not yet have reached the payroll system. Finance needs to consider the relevant obligations and supporting evidence so that the bonus decision is not based on accounts that exclude other costs of achieving the reported performance.
Review Revenue Adjustments and Asset Values
Sales figures may change when customer rebates, returns or contractual price adjustments are assessed. An invoice total does not necessarily represent the final amount the company is entitled to retain. Sales and finance should therefore review known arrangements before presenting profit as the basis for a bonus.
Receivables and inventory also deserve attention. A customer dispute or a cancelled stock order may have implications that were not reflected in the preliminary accounts. Management should investigate the facts and apply the relevant accounting requirements rather than leaving the matter until the annual audit.
The objective is a balanced assessment. Finance should not introduce unsupported adjustments simply to reduce the bonus pool, nor ignore evidence because a lower profit would be inconvenient. Consistent accounting and a clear record of the judgements protect the credibility of the process.
Show the Effect of Adjustments Clearly
Consider a hypothetical company with preliminary profit of S$800,000 before tax and the proposed bonus expense. Its scheme provides for a bonus pool equal to 10% of profit measured on that basis. The preliminary calculation therefore produces an S$80,000 pool.
During the close, finance identifies S$100,000 of omitted supplier costs, S$50,000 of customer rebates and a S$70,000 inventory write-down. Assuming these adjustments are appropriate, the revised pre-bonus profit is S$580,000. Applying the same formula gives a pool of S$58,000, a difference of S$22,000.
This illustration excludes other employer costs and assumes an unambiguous pre-bonus formula. It does not establish that an amount already paid can be recovered. Its purpose is to show how an incomplete close can change a decision even when the percentage and calculation method remain unchanged.
Account for the Bonus Obligation Itself
The bonus is also an accounting matter. Finance needs to assess whether the company has an obligation at the reporting date and whether the amount can be estimated reliably. The payment date alone does not determine when the cost belongs in the accounts.
Under IAS 19, profit-sharing and bonus costs are recognised when the relevant conditions are met, including a present legal or constructive obligation arising from past events and a reliable estimate. Established practices can be relevant to that assessment; describing a payment as discretionary does not resolve every accounting question.
Apply the company’s reporting framework to the actual arrangement. Keep the accounting assessment separate from the cash payment schedule and the internal approval workflow. Where the bonus formula uses profit after bonuses, finance must also calculate that relationship correctly rather than applying a percentage to the wrong starting figure.
Check Whether the Cash Is Available
A supported profit figure does not necessarily mean the company can comfortably fund the payment immediately. Customer receipts may be delayed while supplier settlements, payroll and other commitments fall due. The bonus proposal should include a cash assessment as well as a profit calculation.
Prepare a forecast showing the full payment and applicable employer costs alongside other obligations. Use realistic collection dates and identify any reliance on financing. A large receivable should not be treated as available cash simply because it contributed to revenue.
Cash constraints do not automatically remove an existing entitlement. Management should distinguish what is owed from how and when it can lawfully be paid. If a difficulty emerges, obtain appropriate advice and address it early rather than treating the cash forecast as authority to change agreed terms.
Set the Decision Timetable Before Making Announcements
The pressure to reward staff often peaks before finance has finished the year-end close. That timing can be managed more effectively when the bonus process is planned in advance. Agree on the information required, review dates and approval responsibilities before the year ends.
Where the scheme permits, management may consider a structure involving a preliminary payment followed by a final calculation. Any such arrangement needs clear terms, appropriate approval and careful communication. It should not be introduced retrospectively after employees have been told that a payment is final.
Credon’s management accounting and financial reporting support can be discussed in the context of improving this timetable. More timely reconciliations and clearer reporting help management understand the figures earlier, while responsibility for remuneration decisions remains with the company.
Keep Approval Evidence With the Calculation
A final bonus figure should be traceable to the accounts and scheme terms used. Retain the relevant version of the management accounts, the adjustment schedule and the calculation. Identify who prepared, reviewed and approved the proposal.
Document any management discretion separately. If the company decides to award more than the formula produces, explain that decision and confirm the appropriate authority. A deliberate additional award is different from an unnoticed calculation error.
The payroll instruction should match the approved allocation and total. Reconcile the amounts paid with the authorised schedule and investigate differences promptly. This reduces the risk that a sound overall decision is undermined by duplicate payments, incorrect allocations or an outdated spreadsheet.
Respond Carefully if Payment Has Already Been Made
Discovering a difference after payment requires a factual review. Establish whether the original calculation was incorrect under the scheme, whether the payment was genuinely provisional or whether management approved an amount independently of the final profit.
Do not assume that a lower final result creates an automatic right to recover money or deduct it from future salary. The employment terms, communications and applicable law need consideration. Human resources and appropriate legal advisers should be involved where repayment or changes to future remuneration are contemplated.
Finance should document the amount and circumstances without treating the difference as a recoverable employee debt by default. Management also needs a communication plan that explains the issue accurately. Employees should not be left to interpret an accounting adjustment as an unexplained reversal of an earlier promise.
Use the Audit Appropriately
An annual audit may identify adjustments, but management should not rely on it as the first opportunity to complete the accounts. The company needs its own process for recognising costs, reviewing balances and assessing estimates before using profit for remuneration decisions.
The auditor’s role is to provide an independent opinion on the financial statements within the agreed engagement. That does not automatically extend to certifying every bonus calculation or approving the company’s remuneration policy. If the scheme calls for a separate report, clarify that requirement and scope early.
Where a bonus depends on audited results, align the approval timetable with that condition. Where it uses management accounts, define the required level of completion and review. In either case, the basis should be understood before commitments are communicated to staff.
Improve the Process Throughout the Year
A rushed year-end close often reflects issues that have accumulated over several months. Late supplier information, unresolved customer credits and unreliable stock records make the final result harder to establish. Improving regular reporting reduces the uncertainty surrounding annual bonus decisions.
Review significant estimates and outstanding items periodically. Ask departments to report commitments and commercial changes promptly, and compare earlier estimates with final outcomes. Repeated adjustments in the same area should lead to a process change rather than another year-end explanation.
Management can also monitor an indicative bonus calculation during the year, clearly labelled as provisional. This helps identify whether the scheme is operating as intended and whether the expected payment is consistent with the company’s financial capacity. It should not replace the final assessment or create unintended promises.
Base Recognition on Financial Information the Business Can Explain
Employee bonuses can recognise contribution and support retention, but profit-based arrangements need a dependable calculation process. Clear definitions, complete records and a realistic timetable help prevent preliminary results from becoming commitments that the final accounts cannot explain.
The company should be able to show which profit figure was used, how adjustments were treated and who approved the payment. It should also distinguish the accounting obligation, the employee’s entitlement and the cash required to settle it. Those questions are connected, but they are not interchangeable.
If bonus decisions repeatedly precede major year-end adjustments, discuss the reporting process with Credon PAC. Bringing the scheme terms, management accounts and adjustment history into that discussion provides a practical starting point for improving the financial information supporting future decisions.