
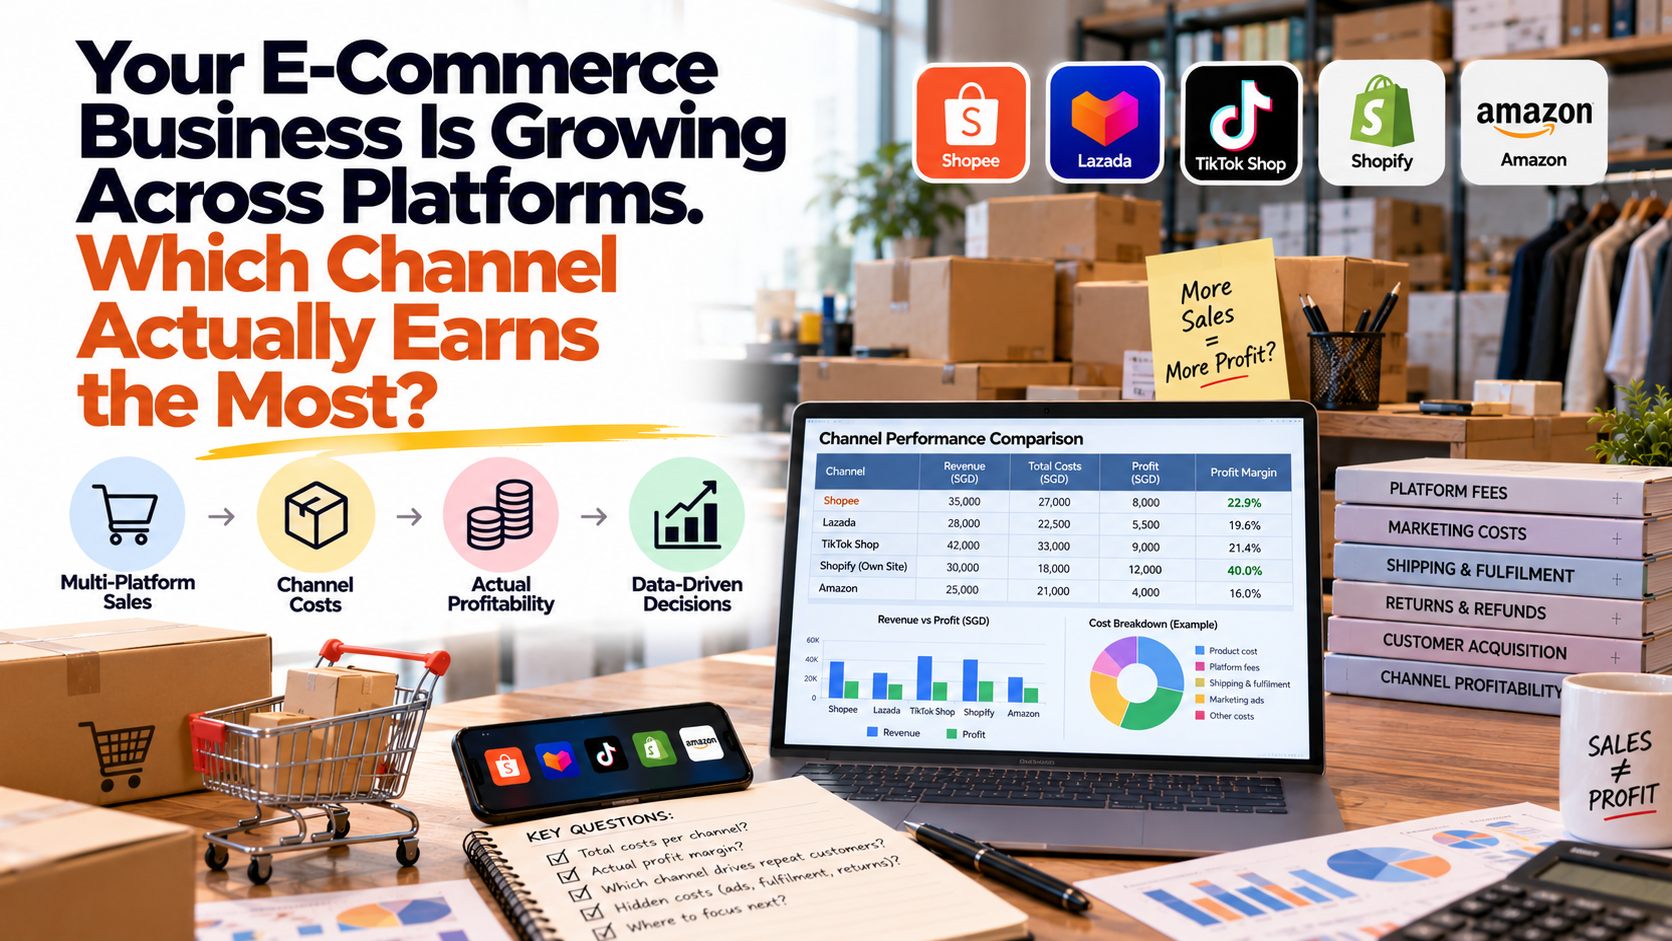
Orders are increasing across your online store, marketplaces and social selling channels. One platform regularly produces the highest sales, another brings more repeat customers, and your own website gives you greater control over the shopping experience. Each appears to offer a reason to invest more.
However, the sales dashboards tell only part of the story. Platform charges, advertising, fulfilment and returns can leave very different amounts behind. The channel generating the most orders may also require the most spending to acquire customers and complete their purchases.
Credon provides accounting and financial reporting support for growing businesses. For an e-commerce owner, meaningful channel reporting starts by connecting sales with the costs and commitments behind them. That creates a clearer basis for deciding where the next marketing dollar, inventory purchase or staff hour should go.
The objective is to understand what each channel contributes to the business and whether further growth is likely to improve the result.
Start With a Consistent Definition of Sales
Different systems can present different versions of the same trading activity. One dashboard may show order values before cancellations, while another focuses on completed transactions. A bank settlement may already have several fees deducted.
Establish a consistent starting point for the comparison. Identify completed sales, seller-funded discounts, refunds and the treatment of taxes collected. Explain how each platform’s figures connect to that basis.
Review shipping income and promotional support as well. If you charge customers for delivery, that income needs to be considered alongside the corresponding cost. If a promotion is partly funded by the platform, distinguish its contribution from the discount your business bears.
Keep the original reports and the adjustments used to make them comparable. Without that explanation, an apparent difference in performance may simply reflect different reporting definitions.
Connect Settlement Reports to the Accounts
The amount paid into your bank account is not a complete measure of channel performance. A settlement may include transactions from different periods, deduct fees and hold back amounts that will be released later.
Prepare a reconciliation between orders, adjustments, fees and receipts. Identify unsettled balances separately so that delayed cash is not mistaken for a missing sale or an expense.
Credon’s bookkeeping services include bank reconciliations and receivables tracking. Those foundations matter when a business receives several overlapping settlement streams. Reliable reconciliations give management greater confidence in the figures used for profitability comparisons.
Resolve unexplained differences before relying heavily on the channel report. A small mismatch repeated across thousands of orders can affect the conclusion, particularly when the remaining margin is already narrow.
Follow the Cost of the Products Actually Sold
Channel comparisons need consistent product costs. Using current purchase prices for one channel and older standard costs for another can distort the ranking.
Connect sales to the appropriate inventory records and apply a consistent costing policy. Include relevant acquisition costs in accordance with the accounting approach used by the business. Keep the cost of unsold inventory distinct from the cost of products sold during the period.
Look at the product mix too. One channel may sell mostly high-margin accessories, while another attracts customers purchasing larger, lower-margin items. A difference in overall margin may therefore reflect what customers buy, as well as how much the channel charges.
Compare similar products across channels where possible. Then review the whole channel separately. Those two views help distinguish product economics from the cost of reaching and serving customers.
Capture the Charges Beyond the Headline Commission
The advertised or contractual commission rate is only one part of the cost. Depending on the arrangement, the business may also pay payment-processing charges, programme fees, fulfilment charges or other service fees.
Use actual invoices and settlement records for the period. Identify which charges vary with sales, which apply per order and which are fixed subscriptions. Review the current terms of the programmes your business has joined rather than relying on an old pricing assumption.
Avoid deducting a fee twice. If the sales figure has already been reduced by a charge, finance needs to recognise that when building the comparison. A consistent report should show clearly whether it starts before or after each deduction.
The same discipline applies to your own website. It may have no marketplace commission, but payment gateways, software and operational support still have a cost.
See How the Sales Ranking Can Reverse
Consider a simplified hypothetical retailer comparing one marketplace with its own website for a month. Figures exclude taxes collected, and net sales already reflect seller-funded discounts and customer refunds.
The marketplace produces S$100,000 of net sales. Product costs are S$45,000, platform and payment charges are S$14,000, attributed advertising costs are S$15,000, and fulfilment plus return-handling costs are S$12,000. This leaves S$14,000 before channel-specific fixed costs and shared overheads.
The website produces S$70,000 of net sales. Product costs are S$31,500, payment charges are S$2,100, attributed advertising costs are S$10,000, and fulfilment plus return-handling costs are S$8,400. This leaves S$18,000 on the same basis.
The marketplace has more sales, but the website contributes S$4,000 more before the excluded costs. Their contribution percentages are 14% and approximately 25.7% respectively.
These figures are illustrative and do not represent actual platform rates. They also do not establish that the website should receive every additional dollar of investment. They show why the sales ranking needs to be tested against a fuller cost picture.
Treat Advertising Attribution as an Estimate
Advertising reports can make channel performance look more certain than it is. A customer may discover your product through a social advertisement, compare it on a marketplace and later buy from your website. Several systems may claim a role in the same purchase.
Choose a documented approach for management reporting and explain its limitations. Separate advertising that is clearly linked to a particular channel from broader brand activity that supports several routes to market.
Do not count the same sale multiple times when bringing advertising reports together. Reconcile attributed results with actual orders and retain a consistent comparison period.
Where attribution materially changes the channel ranking, test alternative reasonable assumptions. Management should understand whether the conclusion remains strong or depends on assigning nearly all shared advertising cost to one channel.
Measure Returns Beyond the Refunded Amount
A refund reduces what the business earns from the sale, but it may not capture the full cost of the return. Collection, inspection, repackaging and customer support can require additional resources.
Determine whether the product can be resold and whether any loss in value needs to be reflected. Keep the refund, inventory movement and handling costs connected so that the same loss is not counted twice.
Consider timing as well. A strong sales month may generate returns in the following period. Comparing channels before those returns become visible can make recent growth appear more profitable than it proves to be.
Use a consistent method for reviewing this effect. An order-cohort report, following sales from a particular period through their return cycle, can complement the monthly accounts and reveal patterns that a single month misses.
Understand What It Costs to Fulfil Each Order
Order volume alone may not explain warehouse effort. A single-item parcel differs from an order requiring several picks, special packaging or delivery to multiple destinations.
Review the activities that create meaningful cost differences. These may include picking, packing, storage, dispatch and customer enquiries. Use reliable measures without making the report unnecessarily complicated.
A channel with a low average order value may require many parcels to generate the same sales as another channel. Conversely, larger orders may involve heavier shipping costs or more complex handling.
Credon’s financial reporting support is relevant to the broader need for organised performance information. For an e-commerce business, finance and operations need to work from connected records so that fulfilment spending can be understood alongside the orders that generated it.
Separate Channel Contribution From Shared Overheads
Shared staff, warehouse rent and management costs must be funded by the business. However, dividing them across channels requires judgment and can materially change the reported result.
Show channel contribution before shared allocations, then present the allocated costs separately. Use a reasonable basis that reflects resource use where practical, and explain the assumptions.
This gives management two useful perspectives: what remains after the channel’s identifiable costs, and how the business covers its overall operating structure. Neither should be confused with the amount that would automatically be saved by closing a channel.
For example, removing a marketplace account may reduce transaction fees while leaving warehouse rent unchanged. A fully allocated loss is a reason to investigate, but the closure decision needs a separate assessment of the costs and receipts that would actually change.
Compare Repeat Customers With Newly Acquired Customers
A channel may look expensive because it is bringing in new customers, while another benefits from an established audience. That distinction can matter when evaluating current performance and future potential.
Separate new and repeat purchases where the available data allows a reliable comparison. Assess the contribution from those orders after the relevant acquisition and service costs.
Avoid justifying current losses with unsupported expectations of future loyalty. Repeat-purchase assumptions should be tested against actual customer behaviour over a suitable period. Revenue from future orders is not the same as their future contribution.
Also recognise that customer identification may be incomplete across platforms. State those limitations rather than presenting a precise lifetime value that the records cannot support.
Ask Whether More Sales Would Have the Same Economics
The best-performing channel today may become less attractive when expanded. Additional advertising may reach a less responsive audience, or growth may require another warehouse shift, more support staff or different fulfilment arrangements.
Prepare an incremental forecast for the proposed investment. Estimate the additional sales, product costs, acquisition spending and operating commitments associated with that next stage.
Compare several realistic outcomes. A campaign that works at the current conversion rate may generate little contribution if advertising becomes more expensive or returns increase.
Also consider whether sales are genuinely additional. If customers move from one of your existing channels to another, the business gains the change in contribution rather than the full value of the transferred sales. Channel growth and company growth are not always the same.
Include the Cash Needed to Support the Channel
Profitability and cash availability are related, but they answer different questions. A channel may require inventory purchases well before sales and release customer collections only after a settlement delay.
Map those payment and receipt timings. Include stock held for promotions, outstanding settlements and the suppliers that must be paid before cash returns.
A channel with a slightly lower contribution may still have a useful cash profile, while a high-margin channel could require substantial funding during expansion. Management needs both views before committing to a larger campaign or inventory order.
Keep unusual withheld balances or disputed settlements visible. They should not disappear inside a general platform balance without an owner and a follow-up action.
Turn the Comparison Into a Management Routine
A useful monthly channel report should reconcile to the accounts while explaining the operational measures that management uses. Show net sales, product costs, selling and fulfilment costs, contribution and significant cash balances.
Review the drivers of change. A weaker month may reflect a deliberate acquisition campaign, a different product mix or a rise in returns. The response should address the cause rather than simply move spending to whichever dashboard looks strongest.
Credon provides accounting, bookkeeping and financial reporting services that can support clearer visibility as businesses grow. For an e-commerce owner, organised records create a stronger foundation for discussing channel performance and testing investment decisions.
The channel that earns the most may not be the one with the largest sales figure. Its value depends on what remains after serving the customer, how much cash it requires and whether the result can be sustained as activity expands.
Contact Credon to discuss your accounting and reporting requirements. A clearer connection between sales, costs and collections can help you choose where to grow with a fuller understanding of what each channel contributes.